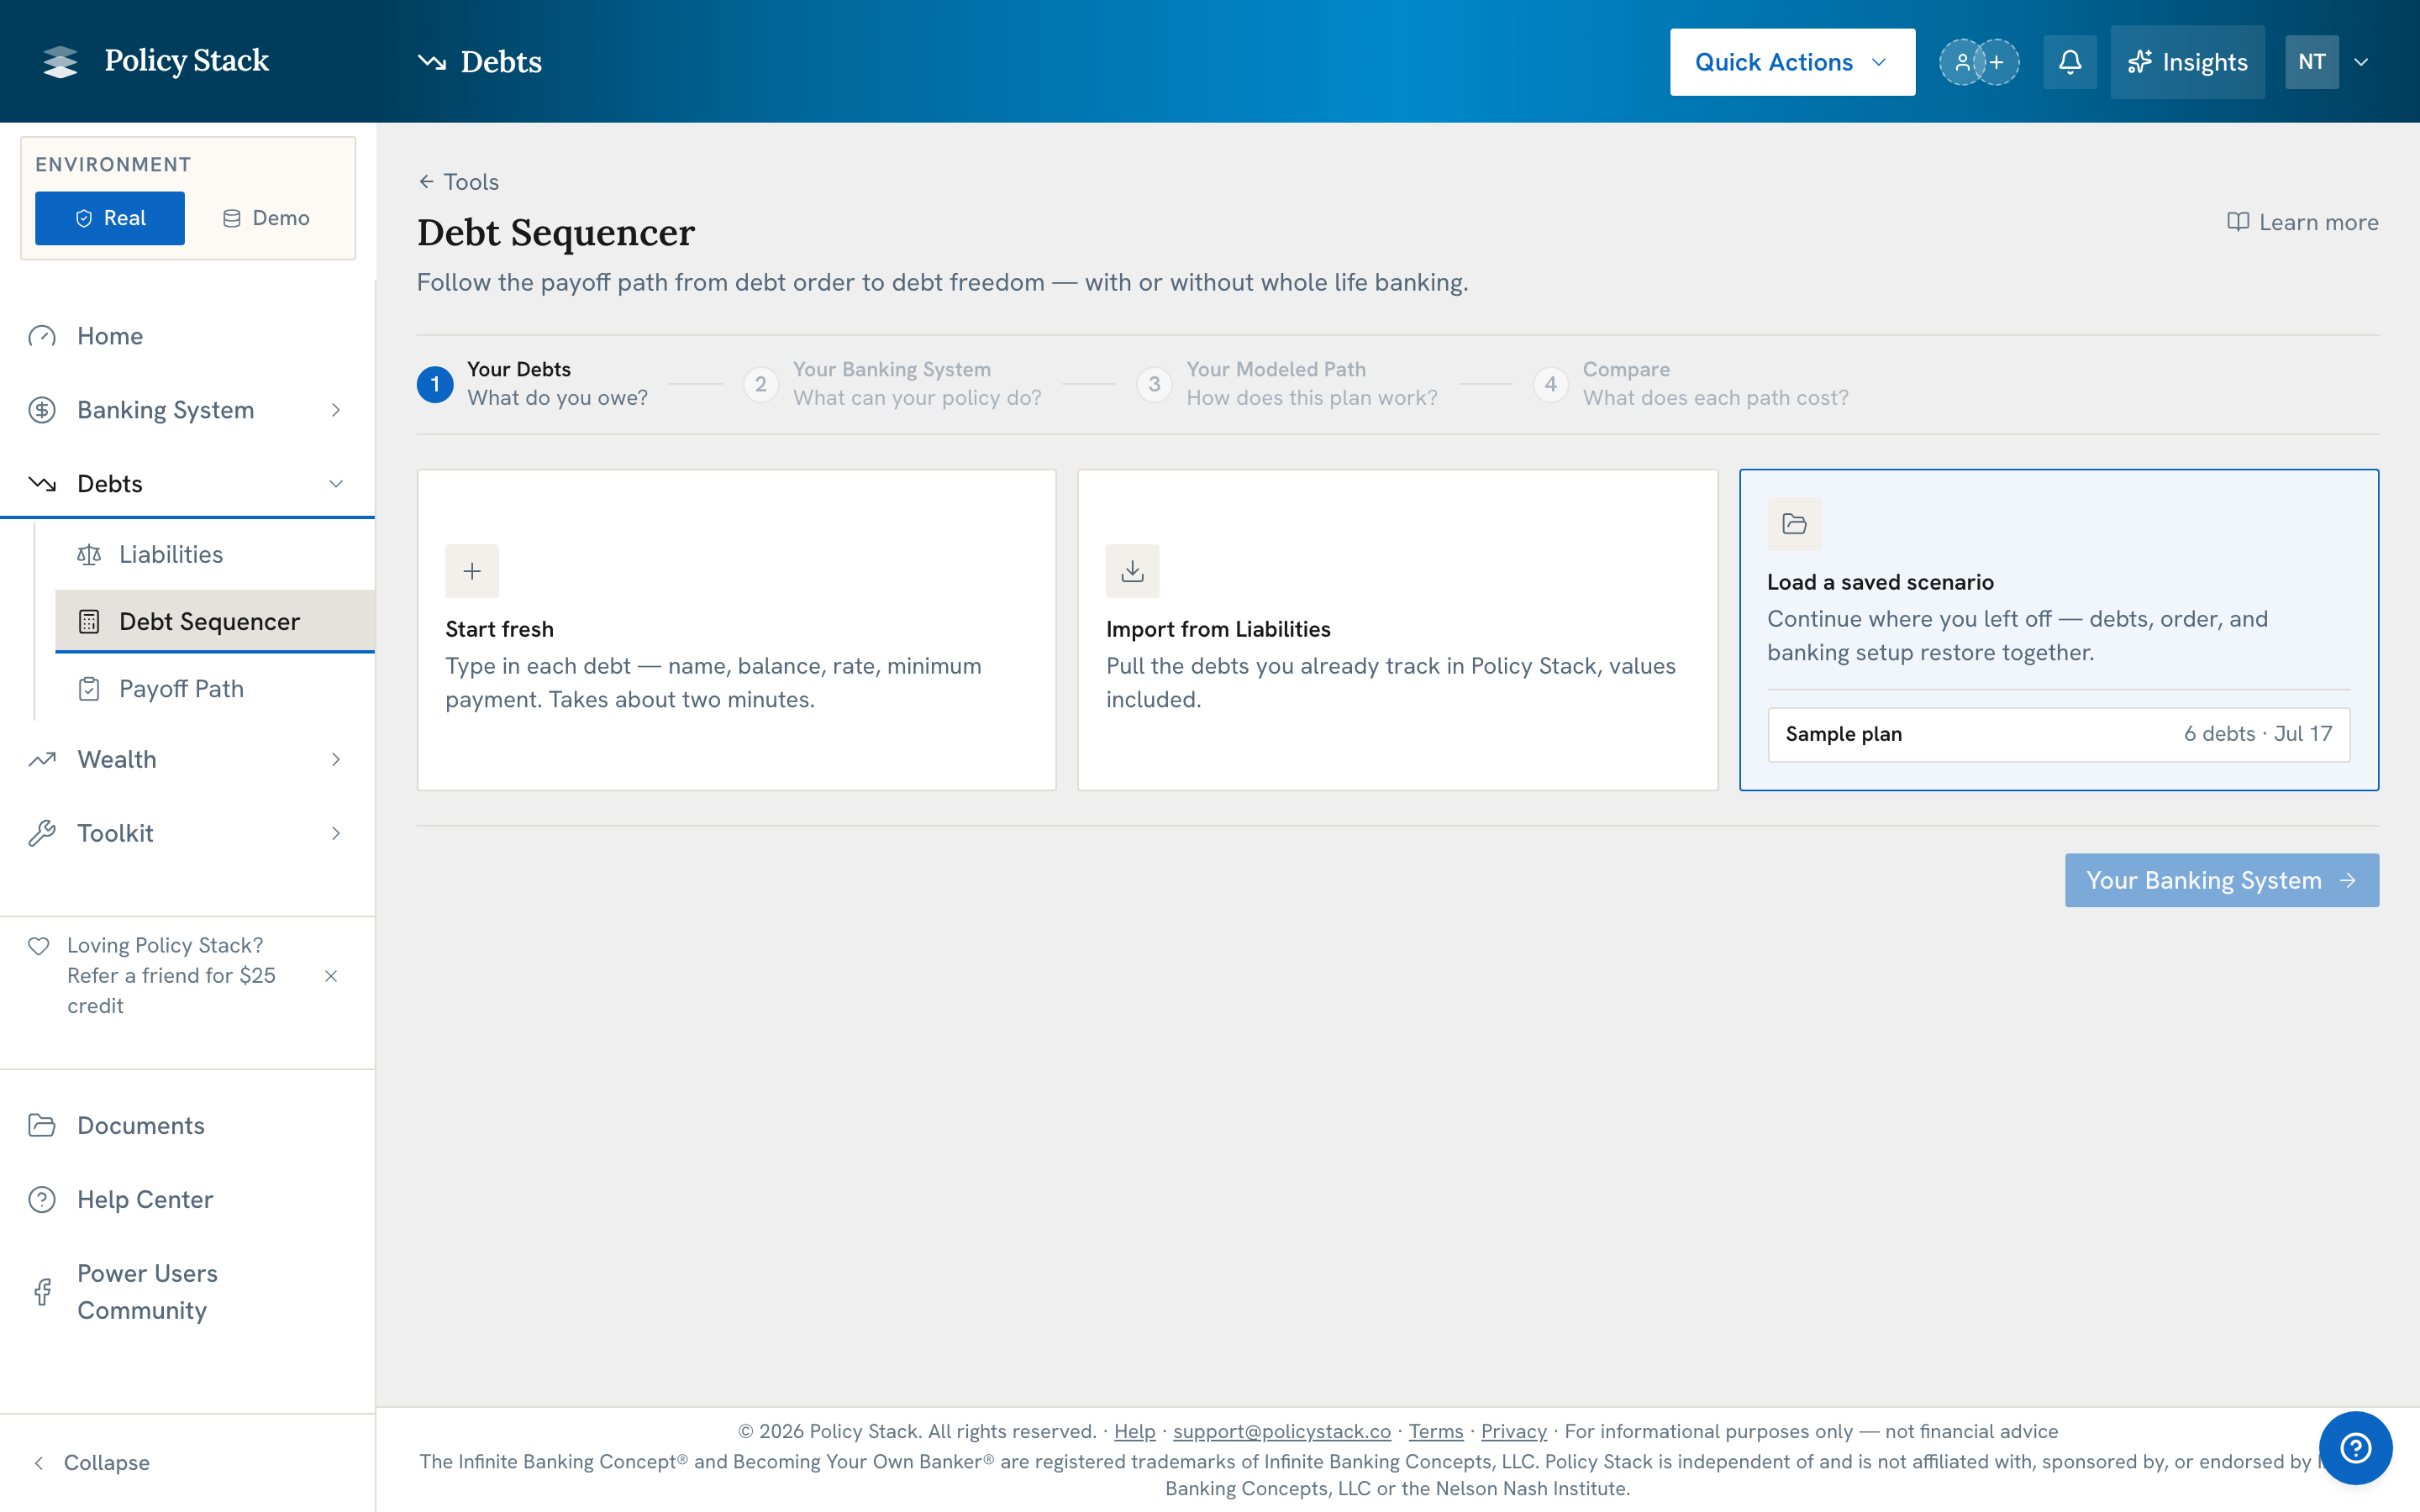
Debt Payoff Path has five stages. Payoff order covers Steps 1–4: compare ways to pay outside debts and model a whole life banking plan that uses and pays back policy loans. Payoff Path is Step 5: track an eligible selected scenario month by month.
This feature requires Builder Pro
What Payoff Order Does
Payoff order uses the debts you enter, such as credit cards, car loans, and mortgages. It compares payoff timing and interest without recommending a plan.
Debt APR and policy-loan rate labels show up to two decimals and omit trailing zeros. The model uses the full rate from its inputs. Cash value to use and kept-back labels show up to one decimal and total 100%. PUA conversion shows up to two decimals. Saved inputs retain their full precision.
Payoff order models how outside debts may be paid off. With a whole life banking layer, it also models policy-loan draws and repayment. Payoff Path tracks a selected eligible plan against recorded monthly payments and balances.
Comparison Panels
Minimum payments only
This path makes only the minimum payment on every debt. It gives you a starting point for comparing the other plans.
What to look for: Total interest paid and how long the payments last. Compare this path with another path to see what the extra monthly money changes.
Highest rate first
This plan sends extra money to the debt with the highest interest rate and pays the minimum on every other debt. When one debt is paid, its old payment moves to the next debt.
What to look for: This approach typically results in the lowest total interest paid over the life of all debts.
Lowest balance first
This plan sends extra money to the debt with the smallest amount owed. When one debt is paid, its old payment moves to the next debt.
What to look for: This plan may pay one debt sooner, even when it does not save the most interest.
Whole Life Banking Strategy
The whole life banking plan uses policy-loan money to pay outside debts. The plan then pays back the policy loan. The policy cash value stays in the policy and may keep growing under the policy terms.
What to look for: This approach models the effect of routing debt payments through your banking system. It shows total interest paid to external lenders vs. loan interest within your system, and tracks how loan repayment keeps your system whole.
The visible Game Plan focuses on the whole life banking path when that layer is configured. Highest rate first and lowest balance first still function as comparison math, but the action sequence shown in the Game Plan stays centered on the policy-loan path.
Configuring the Whole Life Banking Strategy
Step 2 asks one question at a time. Each question is a numbered row: the one you are on is open, the ones you have answered collapse to show your answer, and a question that does not apply to your situation is not shown at all. You can reopen any earlier row to change an answer.
The first question is where the cash value comes from, with three starting situations:
I have a policy — start from your recorded cash value and loan balance
I'm starting one — build the cash value from the premiums you plan to pay
Both — start from your recorded policy, then add one you're planning
You can move back between these choices without losing values already entered. Existing policies contribute their recorded starting capacity; planned policies add separate Modeled capacity streams on the combined path.
For recorded policies, Step 2 counts the full recorded premium, base plus PUA, as money already committed each month.
When no policy can be imported, Step 2 says why: no whole life policy is recorded, none is active or paused, none has a cash value recorded yet, or (for someone other than the account owner) none is visible to you. Enter policy values manually stays available. Choose No policy to model, save and compare debt payments using minimums and extra monthly money, without policy inputs. Monthly tracking still requires a modelable whole life policy. When a policy path is selected, Your Plan and Compare wait for the required Step 2 values. When policy loans aren't in a plan, Step 3 and Compare say so at the top, why, and what to fix in Step 2, including when the plan takes no new policy loans because the loan rate is at or above every debt's rate. A plan without a policy shows no Results cards, because each one is a policy milestone. Debt imports (your debt list, or a client's shared liabilities) are on Step 1. Fresh plans require a paid-off-debt payment choice; existing saved choices stay selected. Cash value to use asks for the percentage available for borrowing; the remainder is kept back. A saved illustration must be confirmed on the policy, not merely uploaded to Documents. Failed saved-illustration lookups offer Retry rather than claiming there is no illustration.
Underneath the questions, an always-visible breakdown — Each month — itemises what your money is already committed to, and ends with the field where you say what you can put toward all of it (monthly or annually, depending on your budget cadence). Policy premiums and debt payments always come from the same funding, so Step 2 states the premium being committed rather than asking where it comes from, and shows a shortfall row when minimum debt payments plus the selected premiums exceed the amount you entered.
There is one special case. When a confirmed policy illustration sets the premium, the tool keeps that premium in the plan and shows how much more money the plan needs each month.
The policy details within those paths use the following approaches:
Use a current policy
You already have a policy with cash value. Enter:
Cash value available for a loan — the cash value the model can use for a policy loan
Policy loan interest rate — the rate charged by the insurance company
Policy values and funding — the policy's recorded Cash Value, its confirmed illustration when available, and the dated premium schedule; manual inputs remain available
The tool uses cash value from the current policy to pay outside debts right away. It may pay all or part of them. The paid outside debt stops charging interest. The policy loan then charges interest, and freed payments follow the plan choice made in Step 2.
When the cash value is not enough for every debt: The tool starts with the first debt in the chosen order. The extra monthly money keeps paying the debts that remain. Automatic loans require enough borrowing room to clear an eligible debt in full. The draw schedule sets when borrowing is checked; selecting Monthly does not require a loan every month.
For a current policy, select the recorded policy to use its own latest Cash Value, available cash value, policy-loan balance, illustration and funding schedule. Base and PUA premium start from the policy’s saved amounts and active funding schedules, independently of payment reminders. Edits apply to this plan only; a saved $0 stays $0. New planned loans are added to the recorded opening loan balance. If you enter a policy manually, provide its starting values, loan rate and annual premium/Cash Value schedule. A forecast starts at recorded Cash Value; a difference from the illustration is carried forward without compounding. Values between policy years are estimated. Unsupported premium or rider details can make the forecast unavailable rather than inventing growth.
For a selected recorded policy with an issue date and a saved annual table, reopening the builder advances the table to the current policy year. The recorded opening cash value stays the anchor; the current printed premium split and remaining growth rows advance with the anniversary.
The starting-value summary shows — when its recorded opening policy-loan balance is unavailable. A recorded zero shows $0. When that recorded amount is missing, modeling uses an applicable saved starting balance, or assumes $0 if none applies.
Start a new policy
You plan to start a new policy. Enter:
Base premium — the regular policy premium
Extra premium — added premium that buys paid-up additions and builds cash value
Policy loan interest rate — the rate charged by the insurance company
For a planned policy, choose its confirmed initial illustration or enter annual values manually. Use Saved Illustration to select a saved source; Upload Update replaces it, and View Schedule opens its annual values. Save and Continue saves the policy source and opens Cash value by year. The tool does not create carrier values from the premium. For one planned policy entered manually, each year's premium follows the premium in Your policy; a year given its own premium keeps it and reads "Set for this year". A manual schedule stops at its last entered year; add years for a longer manual projection. Each planned policy needs its own confirmed initial illustration for a dated forecast; unsupported or unbound multi-policy inputs can remain estimates or unavailable. Sources kept for tracking do not change the plan. For an older illustration, enter the current policy year and current cash value available for a loan; the schedule uses the values provided for those years.
Choose how often premium is paid (monthly, quarterly, semi-annual or annual) and the month or months it is paid in, and enter the amount paid each time. The plan sets aside the monthly equivalent each month; cash value builds in the months premium is paid. This is an estimate, not a promise from the insurance company. A saved plan keeps these choices. The policy-loan draw schedule is separate: Monthly permits draws in any month, Quarterly in plan months 1, 4, 7 and 10, and Annual in months 1, 13 and 25. Draws remain limited by available policy-loan capacity.
For a policy you already have, entered by hand, choose how often its premium is paid (monthly, quarterly, semi-annual or annual) and the month or months it is paid in, and enter the base premium and paid-up additions as billed. The plan shows the monthly amount it sets aside; cash value builds in the payment months. Until a month is chosen, the premium is spread evenly across the months. Imported policies use their recorded frequency and premium due date (or anniversary month), shown beside each policy. Leave both amounts blank and the plan uses the cash value table as entered.
The illustration supplies policy values; the dated premium calendar supplies planned funding. Premium frequency and loan-draw frequency are separate. If the entered base or rider funding cannot be supported by the illustration, the tool shows that the forecast is unavailable instead of treating illustrated premium as paid. Payments after the supported forecast end are excluded. Recorded tracking and Finish month remain available without a forecast; the next month has no projected targets or loan draws.
Unknown payment dates use a disclosed monthly estimate after the recorded Cash Value date. Known paid-up additions dates stay on their own calendar. A simple monthly premium can be edited in Payoff Path; separate, future or one-time schedules are edited in Your Banking System.
Extraction keeps each printed ledger separate. Current (non-guaranteed) end-of-year values are the default illustration source. When a document also contains a guaranteed ledger, you can choose to use guaranteed values instead, and the guaranteed ledger is preserved either way as a separate comparison line — values are never blended across ledgers. A document containing only guaranteed values asks for that choice explicitly.
An inforce illustration is saved for tracking by default. Including it in the projection is an explicit choice made during review. When included, the model starts from the policy's current illustration year, with the confirmed current accessible cash value as opening capacity and the illustration's future rows as growth.
The tool then models a staged loan sequence. As premium builds cash value, a policy loan can clear the next debt. The user may also enter a first policy loan amount that pays only part of the first debt. By default, extra monthly money keeps paying outside debts first, and unpaid policy-loan interest is added to the modeled loan balance each month. The user can instead pay down the policy loan before the next planned loan.
After all debts are paid, the model keeps the monthly money available by default. Sending extra money to the policy is available only after the user enters how much extra premium the policy can accept each month. The model never sends more than that amount to paid-up additions; any amount above the limit stays as cash.
When an illustration or annual values assume more premium than the policy records, the tool counts each year's cash value only for the premium actually paid, built month by month. Paid-up additions and base premium are counted separately when the illustration prints them. The plan shows "Cash value limited to premium paid" when this applies. When an illustration prints the paid-up additions premium separately, on any of its ledgers or on a premium-only schedule such as a PUA rider report, the tool rebuilds its values for the premium entered: base and rider values as printed, paid-up additions from what is paid (each additions dollar adds 90% as cash value unless the illustration prints its own, editable in Fine tuning). When it prints only total premium and that total matches the policy's recorded premium, the tool uses the recorded base and paid-up additions premium for every year printing the same total, and the base alone for later years printing only the recorded base; when they differ, the plan names both totals. You can also enter the illustration's paid-up additions premium and last policy year for that plan ($0 if it assumes none); the entry is labeled Entered, and the illustration stays as uploaded. An entry the plan can't use yet stays saved but isn't shown until it can. Values are projected from the illustration and are not carrier figures.
How to Use Step 1
Navigate to Debt Payoff Path — open Toolkit → All Tools → Debt Payoff Path; the tool opens at Step 1
Add your debts — enter each external debt with its balance, interest rate, and minimum payment, and choose the payoff order: highest rate first, lowest balance first, free a payment first, or your own order
Set your monthly allocation — enter the funding available to the modeled path as a monthly or annual figure; conventional paths keep the debt-only calculation
Add policy facts — choose current policies, a planned new policy, or both; choose the premium that comes from the same monthly money as the debt payments
Review the yearly policy values — choose where they come from: use a carrier illustration, enter values manually, or use example CV growth (a disclosed 4% assumption). When you import recorded policy values and a selected policy has a confirmed Illustration Analytics record, its current values are added to this model automatically; a message confirms you do not need to upload or import it again. If the policy has several, the latest in-force illustration is used. When a newer illustration is confirmed later, the tool says so and Use it swaps it in. A guaranteed-only record still requires an explicit guaranteed-scale choice. Saving Your policy also confirms a ready saved illustration and opens Cash value by year as Saved. Live forecasts use each policy’s own recorded Cash Value and future base/PUA dates; inferred dates are estimates, and unsupported funding may limit future values. Original carrier values remain distinct.
Set the plan choices — in Step 2, choose where each freed debt payment goes: the next debt, the policy loan, or keep the money. With a new policy and confirmed monthly premium room, extra premium is an additional fourth choice that affects modeled Cash Value accumulation using illustration growth and additions value when available, or the configured PUA load when additions value is not printed. For recorded policies, the PUA load is the one saved on each policy; Fine tuning can override it for the whole plan, a pooled plan whose policies differ uses the load of the policy with the highest cash value, and 10% is assumed where none is recorded; when a policy path is configured, Step 3 adds an optional first policy loan amount, where your extra monthly money goes while a policy loan is open and outside debts remain, and an optional destination for the money after your last debt is paid (the payoff order set in Step 1 shows there as read-only).
Review the handoff — confirm the debt order, monthly funding, rollover rule, active period, and policy schedule when applicable
Create and open — save the scenario and open its preloaded Payoff Path
Reading the Results
The comparison panels show:
Months until paid — how many months the plan takes to pay every debt
Total interest paid — the total cost of interest across all debts
Interest saved — how much less interest is paid than with minimum payments only
Monthly payments — how payments change as each debt is paid
Where freed payments go — what the plan does with a payment after a debt is paid
You can save multiple scenarios with different extra payment amounts to explore how changes in monthly allocation affect each strategy.
Reading a policy year month by month
On the modeled whole life banking path, opening a year shows one row for each month. The three columns are Premium put into the policy, Cash value available for a loan, and Policy loan. Read from left to right: premium goes in, cash value changes, and a policy loan may use that value. The year summary shows how much cash value was added, and the grid shows when it happened.
Cash value available for a loan is total cash value minus the policy loan. It matches the total shown in the year row.
The forecast separates dated premium payments from estimated Cash Value growth. The grid shows when modeled borrowing capacity could cover a debt.
The cash value column is not the exact amount the insurance company will lend. The amount entered as Cash Value cushion lowers what the model may borrow. Every value in this grid is Modeled.
Saving a scenario
Saving is available on Your Debts, Your Plan, and Compare — a save from any of them records everything entered so far, including the banking system configured in step 2 and the payoff order and whole life banking layer selected in step 3.
Save As creates a new named scenario.
Save updates the scenario you currently have open, in place. It appears once a scenario is loaded; before that, a single Save Scenario button names and creates the first one.
Loading a scenario is offered on Your Debts only, because loading replaces whatever is currently entered. In that saved-scenario list, use the archive control beside a scenario to move it to Archived after you confirm; restore it from Archived in the same list.
Starting a new plan
Start New appears in the tool header once anything has been entered. It clears the debts, banking system, and settings and returns you to the start screen, where you can start fresh, import from Liabilities, or load a saved scenario. Policy Stack asks you to confirm first.
Clearing is reversible. An Undo banner appears above the tool and restores the entire session — debts, banking system, payoff order, the scenario you had open, and the step you were on. The banner stays until you dismiss it or begin entering a new plan; once a debt exists again, Undo retires rather than replacing the new work.
Saved scenarios are not affected in either case. A scenario you had open is still in the saved list and can be loaded again from that same screen.
From Planning to Monthly Tracking
Payoff order is Step 1 of Debt Payoff Path. Payoff Path is the final step for ongoing monthly tracking. Starting a scenario copies the selected strategy, debt order, starting balances, funding, rollover behavior, modeled milestones, and whole life banking configuration when applicable into a fixed baseline. A household has one active path; starting another moves the previous path to history with its recorded periods intact.
Later edits to the source scenario do not silently rewrite that active baseline. In Payoff Path, record what actually happened, compare the period with the modeled row, close the month after every action is recorded or skipped, and continue with the next period generated from the same saved strategy. With no snapshot of the linked policy dated in the month, recording that month's policy loan first asks for one (Record snapshot) or for a projected value (Use projected value, labelled Projected); finishing a month is never blocked.
Before you begin shows numbered steps that turn into a check marked Done as each is met: link your debts to your Liabilities, use recorded debt balances (add any missing ones), choose recorded policies or save with none selected to keep the plan Modeled (whole life banking plans only), then record your first payment. Setup reuses dated balances already in Liabilities, including those before the path started; confirming a new liability saves its opening balance once. This does not finish the month’s closing balance after payments and interest. A recorded balance doesn't complete the last step. Each step says where it happens and has its own button: Open Liabilities (or Edit plan) to link debts, Record balances to jump to the Action Center's balances, Choose policies, and Start tracking. If the plan has no cash values for policy years 1–5 or an illustration, there is no Action Center yet: those steps send you to Edit plan (or Payoff order) to add them, and recording starts once they're added. A new path records payments, skips, and policy loans only after the steps before Start tracking; Once your debts are linked, Record balance stays available, because recording balances completes the balances step. A recorded balance alone doesn't start tracking. The Action Center says which step is next and links to it. A path that has already recorded keeps recording and shows a Finish setup reminder instead. Once everything is done, the card reads Ready · tracking since the first recording's date for that month, then hides. Policies selected in an existing-policy plan carry forward; the first eligible one is the loan action target.
Step 5 directly shows the same Year by year table and expandable monthly money map as Step 3. Past months show dated recorded payments, balances and available policy history. Future months re-project from the newest recorded data. Missing history stays unavailable; a projected value never fills a recorded cell. Use Refresh data after updating another source; returning to the tab also refreshes it.
This month's recording happens in the Action Center, below that table. On the separate tracking page it remains above Month by month: Record payment, Record balance, Skip, and Finish the month. In Month by month, this month is a summary row with a Record in Action Center link.
The Month by month card has two views. Summary lists each month's totals. Every debt is a read-only spreadsheet for the same year: the policy loan balance and what is available for a loan first, then one column per debt in payoff order, then the balance left. Each cell shows the debt's balance, what was paid (Show payments), and when it is paid off. Nothing is entered there: it updates from what you record in the Action Center, and every later month re-projects from it. Recorded months show recorded values and how far each is above or below the plan.
The Game Plan
The Game Plan turns the whole life banking path into a month-by-month sequence:
Monthly budget — set the total you put toward debt each month; it never drops below your combined minimum payments
Debt-free date — the projected month you clear the last debt, with total months and total interest
Focus steps — a numbered order showing the modeled sequence, monthly payment, clear date, and interest on each debt
Policy path — a policy loan can pay all or part of the first debt, later loans can clear other debts, and Compare shows policy value and cash kept in the same ending month as the path without policy loans. Both paths spend the same monthly money: a policy you already own keeps its premium on both; a planned policy's premium goes to debts on the path without it
All Game Plan figures are Modeled and illustrative.
Policy Stack is a tracking and visualization tool. It does not provide financial advice, recommendations, or opinions on what you should do with your banking system.
Policy Stack is independent of and is not affiliated with, sponsored by, or endorsed by Infinite Banking Concepts, LLC or the Nelson Nash Institute.